

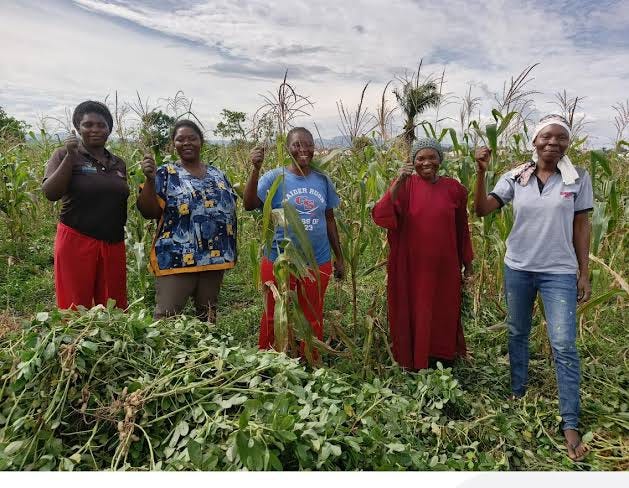
Financial institutions, agribusiness leaders and government stakeholders convened in Uyo, Akwa Ibom State. The meeting aimed to develop cash-flow-based lending products and digital financial tools for farmers.
Nigerian farmers struggle to access credit. Banks view agriculture as high-risk. Collateral requirements exclude smallholders. In 2021, the Central Bank of Nigeria (CBN) introduced the Anchor Borrowers’ Programme. It provided loans to farmers. Repayment rates were mixed. In 2023, the CBN launched the Agricultural Credit Guarantee Scheme. It had limited reach. The current meeting focuses on cash-flow-based lending. This model assesses repayment capacity based on expected harvest income rather than collateral.
The Uyo meeting brought together banks, agribusiness firms and government agencies. The goal is to design financial products tailored to farmers’ needs. Digital tools are central. Mobile apps can track farm activities, verify yields and process payments. This reduces risk for lenders. It also builds credit histories for farmers. The approach mirrors models in Kenya and India. In Kenya, M-Pesa-based lending has reached millions of smallholders. Nigeria’s mobile money sector is growing. The infrastructure exists. The challenge is adoption and trust.
The cash-flow model requires accurate data. Crop yields, market prices and weather patterns must be predictable. Nigeria’s agricultural data is weak. The model also requires stable markets. If prices collapse at harvest, farmers cannot repay. The meeting did not announce specific products or timelines. It was a planning session. The test is whether it produces results.
Winners: Farmers, if they gain access to credit. Banks, if they find a profitable model. Agribusiness firms, which gain supply chain stability. Fintechs, which provide digital tools. Losers: Farmers without mobile access. Banks that cannot adapt. The government, if the initiative fails. Taxpayers, if subsidies are needed.
Bottom Line: Cash-flow lending is the right model. Nigerian farmers need credit, not collateral demands. Whether banks can execute it depends on data, technology and trust.