

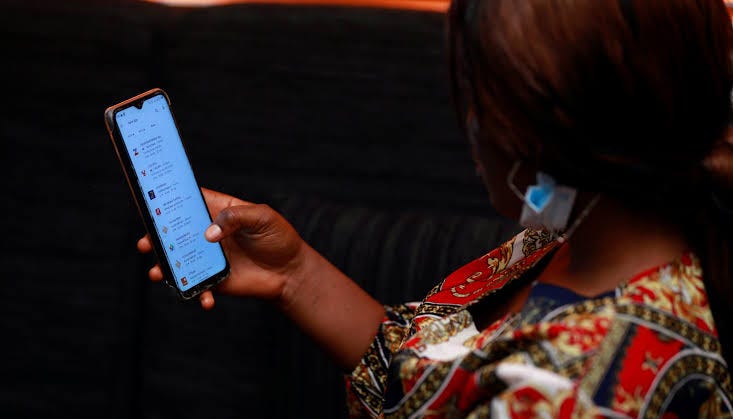
A service outage has tested Nigeria’s growing dependence on mobile banking. The disruption hit users across multiple platforms. Transactions failed. Transfers stalled. Customers could not access balances. The outage exposed how deeply mobile banking has embedded itself in daily life.
Nigeria’s mobile banking revolution accelerated during the COVID-19 pandemic. Lockdowns pushed millions online. The Central Bank of Nigeria (CBN) promoted cashless policies. Point of Sale (PoS) terminals spread across markets. By 2024, electronic transactions had crossed hundreds of trillions of naira annually. The cashless policy of 2023, which limited cash withdrawals, deepened the shift. Banks closed branches. Apps became the primary interface.
The outage affected users of major banking apps. Some reported failed transfers. Others could not pay for goods or services. The disruption lasted hours. Banks blamed technical faults. The CBN has not issued a detailed statement. The Nigeria Inter-Bank Settlement System (NIBSS), which processes interbank transfers, has not explained the cause.
The timing is revealing. Mobile banking now handles salaries, school fees, market transactions, transport payments and utility bills. When it fails, the economy does not pause. It jams. A trader in Onitsha cannot receive payment. A worker in Lagos cannot send money home. A student in Kano cannot pay fees. The outage is not an inconvenience. It is an economic stoppage.
The structural problem is concentration. A few platforms handle most transactions. When one fails, the others strain under the load. Redundancy is limited. Backup systems exist on paper. In practice, they are not tested at scale. The CBN has issued guidelines on operational resilience. Enforcement is another matter.
The outage also raises questions about consumer protection. When transactions fail, who bears the loss? Banks often blame network issues. Customers are left to dispute charges. The dispute resolution process is slow. The outage is a stress test. Nigeria’s financial system did not pass cleanly.
Winners: Cash, which regained temporary relevance. PoS operators with offline capacity. Fintech firms with resilient systems. Losers: Bank customers, who could not transact. Small businesses, which lost sales. Banks, whose reliability is questioned. The CBN, which faces scrutiny over oversight. The cashless agenda, which depends on system uptime.
Bottom Line: Mobile banking is now infrastructure. When it fails, the economy stops. Nigeria has not built it to that standard.