

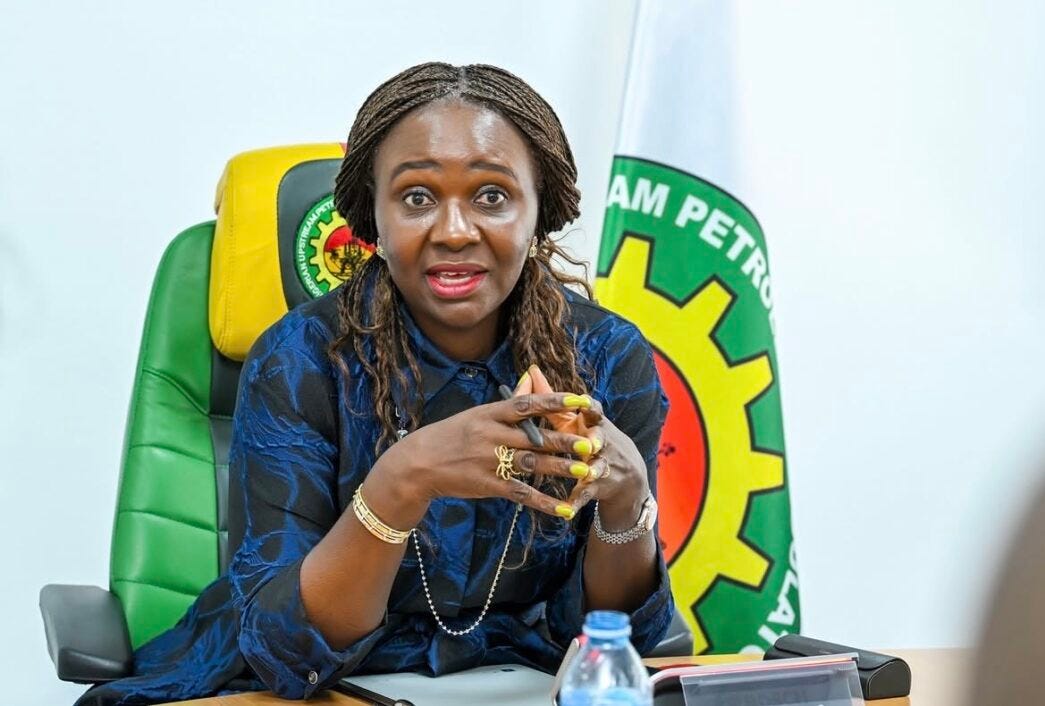
The Nigerian Upstream Petroleum Regulatory Commission approved 145 new well-drilling operations, 595 well re-entries and 39 field development plans in 2026. The chief executive, Oritsemeyiwa Eyesan, gave the figures at an oil conference in Lagos on 10 November. She said faster regulatory approvals had cut project delays and operating costs, supporting production targets.
The rig count is the number to watch. Nigeria has more than 100 drilling rigs and 46 were active in 2026, an increase of more than 300% from 2021. Rigs are the closest thing the sector has to a leading indicator. A rig on site means a budget approved, a contractor mobilised and a well about to be drilled. A rise of that size in four years is not a press release. It is a change in behaviour.
Eyesan also said seismic companies had invested more than $100 million since the Petroleum Industry Act took effect. Exploration spending is the part of the cycle that governments usually cut first and regret longest. The last time Nigeria ran a serious exploration campaign was in the 1990s, when the deepwater acreage was opened. That campaign took a decade to produce the fields now in decline.
Now the constraint that the figures do not address. Nigeria has missed its OPEC quota repeatedly, and the shortfall is not only a drilling problem. It is a pipeline problem, a terminal problem and a theft problem. The regulator says it is intensifying efforts against crude theft, which is the right target. A new well that feeds a tapped pipeline produces a loss, not revenue.
The human arithmetic matters too. For a community in Ogoni or Ilaje, a new well means flaring, traffic and a compensation claim. For the federation account, it means revenue that funds the allocation shared each month. For a family in Kano, it means a possible reduction in the borrowing that pays for roads, if the oil actually reaches the terminal.
The comparison worth making is with the marginal field programme of 2003, which awarded dozens of small fields to indigenous operators. Many never produced a barrel, because the award came without finance, technical partners or evacuation capacity. Approvals are cheap. Barrels are expensive.
The winners are the service companies, the rig crews, and the states that host the new activity. The losers are the communities that bear the flaring and the spill, and the federation, if the barrels get stolen before they are sold.
Winners: Service contractors, rig owners, seismic firms, host states. Losers: Host communities facing flaring and spill. The federation account, if theft eats the volume.
Bottom Line: Forty-six active rigs is real progress. Until the pipeline and terminal bottlenecks clear, the barrels will be counted and not sold.