

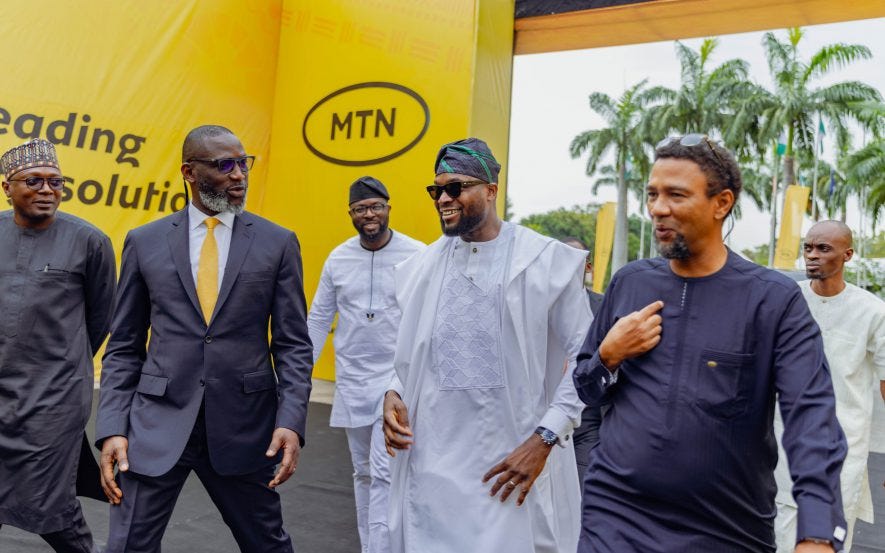
MTN Nigeria has 104.6 million mobile subscriptions and 86.5 million internet subscribers, making the country its largest operating market. The group’s total base across Africa stands at 317.7 million. A revived bid to acquire South African rival Telkom would add more than 25 million subscribers, pushing the combined group toward 348 million. MTN has also agreed to buy out the 75% of IHS Towers it does not already own, in a deal valuing the tower company at about $6.2 billion.
The mechanics of the Nigerian number deserve attention. A 104.6 million subscriber base in a country of roughly 230 million people implies that nearly half the population holds an MTN line. That is market dominance by any measure. But subscriber counts are not revenue. ARPU in Nigeria is low, the naira has weakened sharply, and the cost of diesel to run base stations has eaten into margins. The Telkom deal is a South African play. The IHS deal is an infrastructure play. Neither solves the Nigerian problem, which is that the customer base is large, poor and expensive to serve.
This echoes the 2022 collapse of the earlier Telkom talks, when exclusivity and regulatory concerns killed the deal. It also mirrors the longer pattern of MTN’s Nigerian dominance being both its greatest asset and its greatest regulatory liability, from the 2015 SIM card fine to the repeated tower lease disputes.
The winners are MTN shareholders, who get a larger continental footprint, and South African regulators, who get to decide whether concentration is a price worth paying. The losers are Nigerian consumers, who face a market with fewer credible competitors, and smaller operators like Cell C and Rain, who will face a stronger incumbent.
Bottom Line: 104.6 million subscribers is a Nigerian story. The next 25 million are a South African one.