

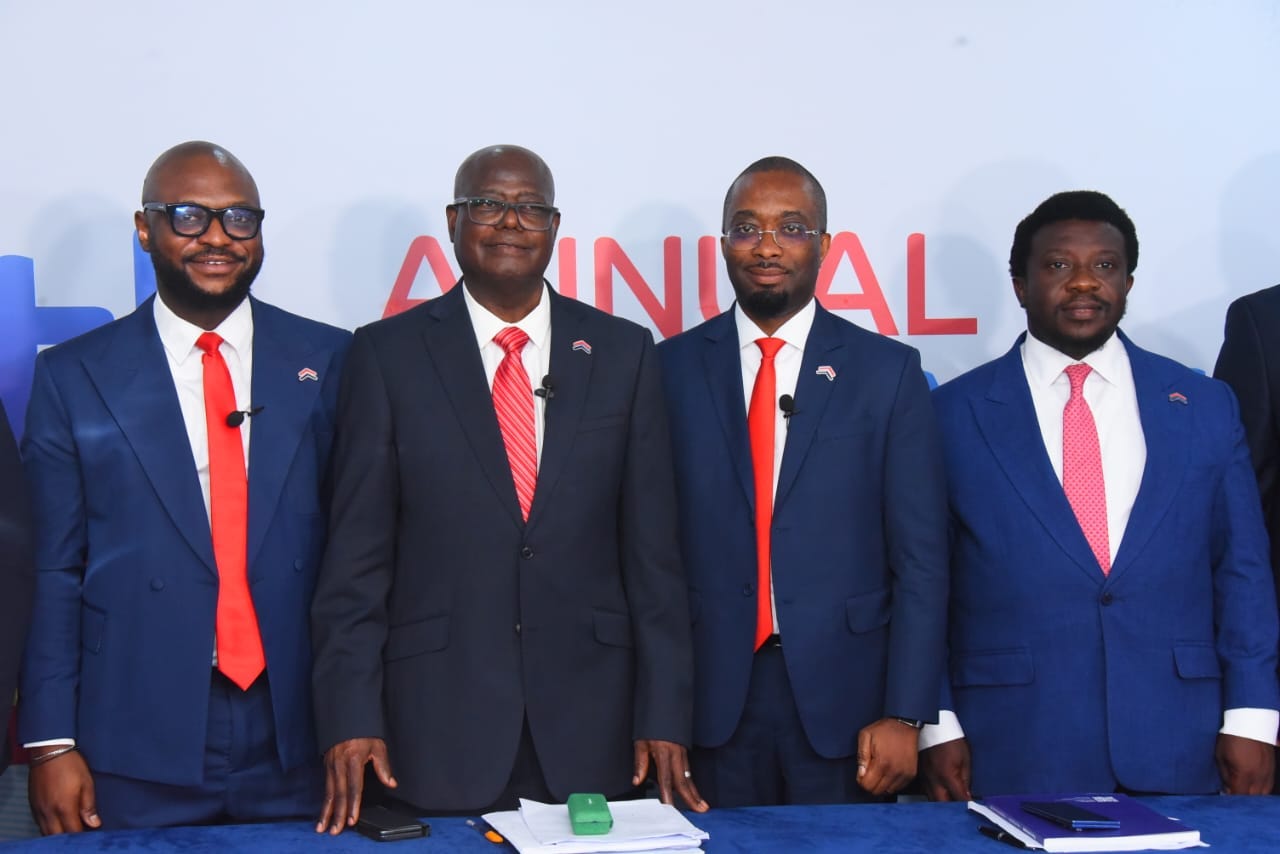
Five prominent investors have collectively acquired a 72.35% controlling equity stake in Abbey Mortgage Bank Plc. The acquisition followed a private placement transaction. The deal reshapes the bank’s ownership structure. It also injects new capital. The investors were not named in the announcement. The transaction was recently concluded.
Abbey Mortgage Bank has a long history. It was incorporated in 1992. It was formerly known as Abbey Building Society. It provides mortgage financing and property development loans. The bank has faced capital challenges. In 2021, it struggled to meet regulatory requirements. In 2023, it announced a recapitalisation plan. The private placement is part of that effort. The Nigerian mortgage sector is underdeveloped. Mortgages account for less than 1% of GDP. High interest rates and land title problems limit growth. Banks in the sector need capital and expertise.
The private placement gives the five investors control. They will likely appoint new board members. They may change management. The bank’s strategy may shift. The investors could focus on retail mortgages, commercial property or affordable housing. The details are not yet public. The transaction values the bank at an undisclosed amount.
The acquisition is significant for the mortgage sector. It shows investor interest. It also shows that consolidation is happening. Smaller banks are attracting capital. The new owners may bring operational expertise. They may also bring connections to the real estate industry. That could help Abbey grow its loan book.
The regulatory angle matters. The Central Bank of Nigeria (CBN) must approve the change in control. The Securities and Exchange Commission must approve the private placement. Both approvals were likely obtained before the announcement. The CBN has encouraged recapitalisation in the banking sector. Mortgage banks are included. The new capital strengthens Abbey’s position.
The risks are real. The mortgage market is difficult. Borrowers struggle to repay. Interest rates are high. Property titles are often disputed. The new owners must navigate these challenges. They must also integrate their strategies with existing operations. The bank’s staff and customers will watch for changes.
Winners: The five investors, who gain control. Abbey Mortgage Bank, which gains capital. Existing shareholders, if the bank becomes more profitable. The mortgage sector, which gains a stronger player. Losers: Minority shareholders, whose stake is diluted. The previous controlling shareholders, who lose influence. Borrowers, if the new owners raise interest rates or tighten lending. The bank’s management, which faces uncertainty.
Bottom Line: Five investors now control Abbey Mortgage Bank. The private placement brings capital and new direction. Nigeria’s mortgage sector needs both. The deal is a vote of confidence. The test is whether the new owners can grow the loan book profitably.