

The Federal Government will link interest on late tax payments to prevailing market rates from October 1, 2026. Under the new order, interest on tax payable in naira will be charged at the Central Bank of Nigeria’s monetary policy rate plus one percentage point. The previous framework applied a five-percentage-point spread.
This means that since the MPR is 23 per cent, taxpayers who pay late will be charged 24 per cent interest on the delayed tax. That rate is subject to the 364-day treasury bill yield floor. For tax payable in foreign currency, the interest rate will be the secured overnight financing rate plus six percentage points.
The Ministry of Finance said the new rates would provide taxpayers with greater certainty over the cost of late payment. The rates will be linked more closely to prevailing market conditions. One interest rate will apply for each calendar month and will be determined on the last business day of the preceding month. The Nigeria Revenue Service must publish the applicable rate on its website by the third business day of every month.
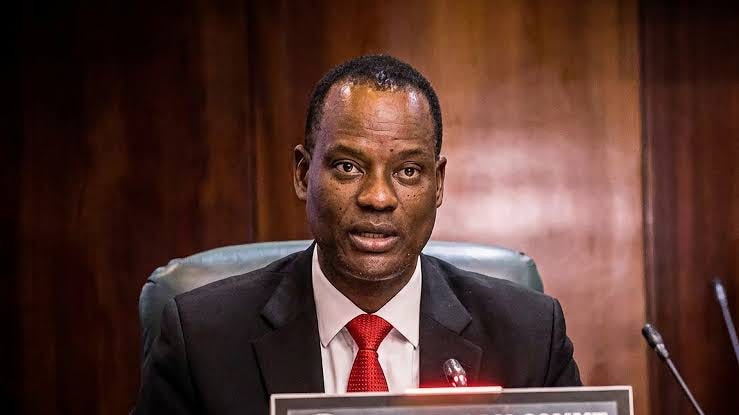
Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, said the framework would ensure that delaying tax payments does not become a cheaper source of credit than borrowing from the market. “Tax that is due belongs to the public,” Oyedele said. “When it is paid late, Government may have to borrow to fill the gap, and the cost falls on everyone.”
Oyedele said the arrangement would provide a uniform basis for taxpayers dealing with federal, state and FCT tax authorities. “Every taxpayer, whether dealing with the Nigeria Revenue Service or a State revenue service, will know the rate in advance, see it published every month, and be charged in the same way,” he said.
The order does not change the 10 per cent penalty for late payment provided under section 65 of the Nigeria Tax Administration Act, 2025. The ministry said relevant tax authorities may waive interest or penalties where good cause is shown, in line with section 66 of the Act. The new rates will apply to interest arising from October 1, including interest on tax that became due before that date. Interest that arose before October 1 will not be affected.
This mirrors the 2017 notice on interest on unpaid taxes, which the new order supersedes.
Winners and Losers
Winners: Compliant taxpayers, who face a more predictable framework. State revenue services, which gain a uniform basis for calculating interest. The Federal Government, which reduces the incentive to use tax arrears as cheap credit.
Losers: Tax defaulters, who lose the subsidy implicit in the previous five-percentage-point spread. Businesses with cash-flow challenges, which may face higher effective borrowing costs on delayed tax payments. Foreign-currency taxpayers, who face SOFR plus six percentage points.
Bottom Line: Tax arrears should not be cheaper than bank credit. The government has closed that gap. The test is whether compliance improves or simply shifts the burden to those least able to pay on time.