

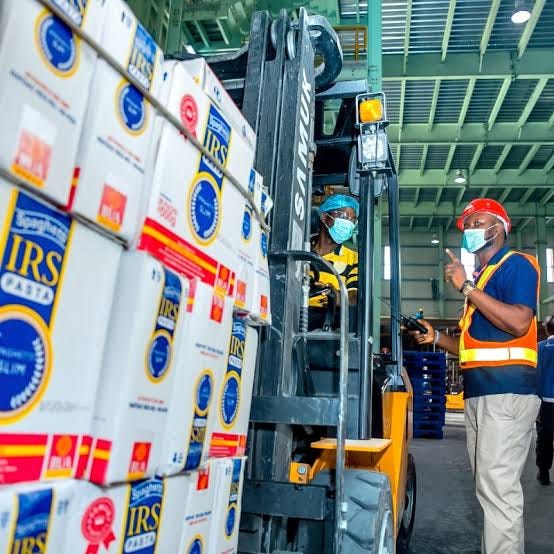
BUA Foods recorded a profit after tax of ₦450.47 billion for the first nine months of 2026. That represents an 11.15 per cent increase from ₦405.27 billion in the same period of 2025, according to unaudited financials published on Friday.
The headline is the divergence between revenue and profit. Turnover fell 19 per cent to ₦1.15 trillion from ₦1.4 trillion a year earlier. Weaker sales in the bakery flour and fortified sugar businesses drove the decline. Profit rose anyway.
The mechanism was cost. BUA Foods cut spending on raw materials by 37.2 per cent. That pulled cost of sales down and lifted gross profit by ₦32.2 billion to ₦552.9 billion. Administrative expenses dropped more than a quarter to ₦22 billion. Selling and distribution expenses fell 15.4 per cent to ₦45 billion. EBITDA margin jumped to 43.6 per cent from 31.3 per cent. Profit before tax rose 11.1 per cent to ₦480.5 billion.
Chief Executive Ayodele Abioye framed the result as deliberate. “Despite a 19% decline in revenue to ₦1.15 trillion, driven by softer pricing conditions and subdued consumer demand, we maintained a substantial improvement in profitability through effective cost optimisation, improved productivity, and rigorous execution across the business,” he said.
This mirrors the classic defensive playbook for a consumer staples company in an inflationary market. When consumers cannot absorb price increases, volumes fall. When volumes fall, revenue falls. The way to protect profit is to compress costs. BUA did that aggressively. The question is how much cost can be taken out before the business starts shrinking its capacity to grow.
The strategic context is BUA Foods’ position as a majority-owned asset of Abdulsamad Rabiu, with a market value of ₦13.7 trillion. The company combined its sugar, rice, oil, flour and pasta divisions into a single entity in December 2021 to capture economies of scale. The nine-month numbers suggest those economies are being harvested.
The consumer story is less comfortable. A 19 per cent revenue decline in a food company is not an abstraction. It means Nigerians are buying less flour, less sugar, less pasta. Consumers are trading down, buying smaller quantities or switching to cheaper substitutes. BUA’s profit rose because it cut costs. Its customers cut consumption.
Winners and Losers
Winners: BUA Foods shareholders, who see profit growth and margin expansion. Abdulsamad Rabiu, whose controlling stake gains value. Management, which demonstrated cost discipline under revenue pressure.
Losers: Nigerian consumers, who are buying less food or cheaper substitutes. Bakery flour and fortified sugar businesses within the group, which drove the revenue decline. Employees, if the administrative and distribution cost cuts included staffing reductions.
Bottom Line: An 11% profit increase on a 19% revenue decline is a cost story, not a growth story. BUA Foods protected its bottom line. The question is whether it can grow the top line when consumer demand recovers. Cost cuts have a floor. Demand does not.