

African airlines recorded an 8% increase in international passenger demand in September 2026. That is the second-highest growth among global regions. Only Latin America grew faster, at 8.2%. The International Air Transport Association released the figures in its monthly passenger market report. The growth outpaced the global international market’s 0.4% increase.
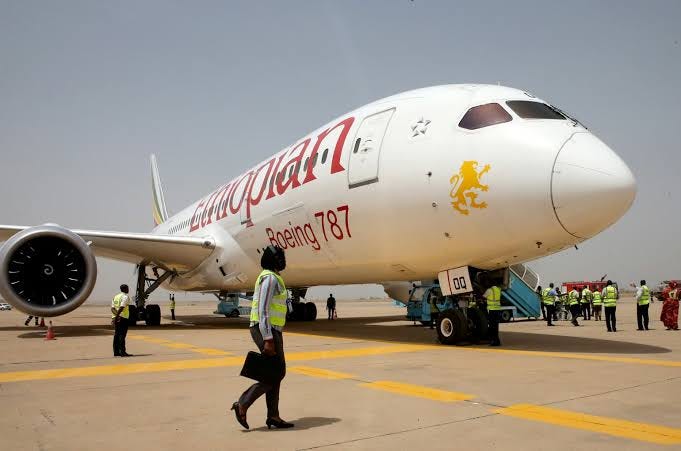
African aviation has expanded steadily since the post-pandemic recovery. In 2025, IATA recorded 7.8% traffic growth for African carriers. It forecast another 6% for 2026, ahead of the global rate. The continent’s airlines have benefited from rising connectivity, new routes and a growing middle class. Intra-African capacity rose 10.5% in August 2026, according to the African Airlines Association. But profitability remains thin. The continent’s carriers earn among the lowest revenue per passenger globally. Demand growth does not always translate into margin growth.
The September figures show a familiar pattern. Demand rose 8%, but capacity rose faster, at 8.8%. That pushed the load factor down 0.6 percentage points to 74.8%. More seats were available, but fewer were filled. That is a warning. Airlines are adding capacity more aggressively than the market can absorb. The result is pressure on yields.
The global picture was weaker. Total passenger demand fell 0.5% year on year. International demand rose just 0.4%. Domestic demand fell 2.2%. The Middle East recorded the sharpest decline, with demand down 7.5%. North America was flat. The weakness was concentrated in those two regions. Excluding the Middle East, international demand would have grown 1.7%.
IATA’s Senior Vice President for Sustainability and Chief Economist, Marie Owens Thomsen, attributed the global weakness to the Middle East and North America. She noted that September improved on August. She warned that geopolitical uncertainty and volatile fuel prices could continue to affect performance. IATA projected global seat capacity growth of 0.6% in October and 1.5% in November.
For African carriers, the demand is there. The challenge is converting it into profit. The load factor decline suggests overcapacity. Fuel costs remain volatile. The naira’s weakness directly affects Nigerian carriers. The continental market is growing, but the economics are fragile.
Winners: African airlines, which gained passengers. Aircraft lessors, which gained demand for capacity. Airports, which gained traffic. Travellers, who gained more route options. Losers: Airlines that expanded capacity faster than demand, which face lower load factors. Carriers exposed to fuel price volatility. Nigerian airlines, which face currency risk. The Middle East carriers, which lost demand.
Bottom Line: Eight per cent demand growth is strong. The load factor fell. Capacity is outrunning demand. African airlines must manage expansion carefully. Growth without profit is not sustainable.