

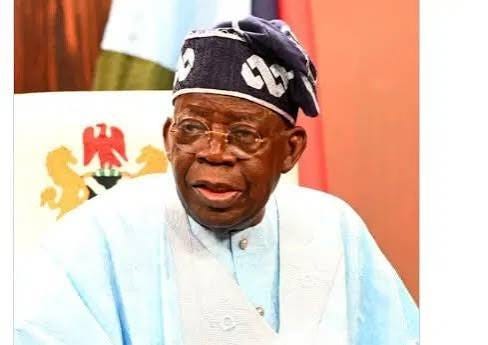
Eligible Nigerians can now access mortgages of up to ₦100 million at a fixed interest rate of 9.75%, repayable over 20 years with a 10% deposit. President Bola Tinubu announced the terms on Tuesday, framing them as part of the economic reforms he began in 2023. More than 2,300 Nigerians across 27 states have already drawn ₦160 billion from the ₦1 trillion Ministry of Finance Incorporated Real Estate Investment Fund (MREIF). The President said applicants should not need a minister or a governor to benefit. He also announced that the Federal Mortgage Bank of Nigeria (FMBN) had been strengthened to offer loans of up to ₦50 million at 6% over 30 years.
The numbers deserve a closer look. On a ₦10 million property, a buyer puts down ₦1 million and pays about ₦85,400 monthly for 20 years. For a formal-sector worker earning ₦300,000 a month, that is manageable. For the majority of Nigerians who earn in the informal economy, with no payslip and no verifiable income, the product is invisible. The scheme also relies on a housing stock that does not yet exist at the required scale. Nigeria’s deficit is estimated at more than 20 million units.
This echoes earlier housing finance initiatives, from the National Housing Fund to the Family Homes Fund, each launched with similar promises and each constrained by the same problems: high construction costs, unclear land titles, and lenders who prefer government securities to mortgages.
The winners are formal-sector borrowers with stable incomes, developers who can access a new credit channel, and the fund managers collecting fees. The losers are informal workers, renters who remain outside the mortgage market, and anyone who remembers the last fund that was going to solve housing.
Bottom Line: A 9.75% mortgage is a real improvement. It is not a housing policy.