

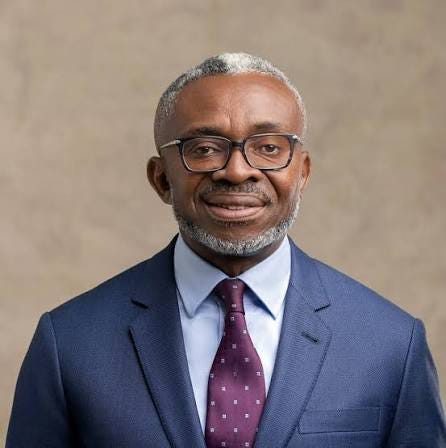
Nigeria’s ₦32 trillion pension industry is facing a growing shortage of investable products capable of channelling long-term savings into productive sectors of the economy. Ike Chioke, group managing director of Afrinvest (West Africa), said the challenge facing Nigeria’s capital market is increasingly not the availability of capital, but the ability to create investment products capable of absorbing the funds productively.
“Yes, ₦32 trillion in the pension industry, the capital is not the issue. It’s actually the investable product,” Chioke said at the Association of Issuing Houses of Nigeria symposium marking its 30th anniversary.
This mirrors the structural paradox of Nigeria’s pension sector. The Contributory Pension Scheme has accumulated assets at a remarkable pace since the Pension Reform Act of 2014. But the domestic capital market has not developed the instruments to absorb those assets at scale. Pension fund administrators are constrained by regulation to invest in relatively safe, liquid assets. Government securities absorb the bulk of allocations. Equities and corporate bonds take a smaller share. Infrastructure, which requires long-tenor patient capital, remains underfunded because the pipeline of bankable projects is thin.
Chioke said the scale of Nigeria’s infrastructure needs presented significant opportunities for issuing houses to develop products that could channel pension assets into roads, power, housing and ports. “Looking at the massive need for Nigeria, the challenge for AIHN is to create more products to address infrastructure development,” he said.
Adama Babaduko, deputy director at the Securities and Exchange Commission, said Nigeria already has several capital market instruments capable of supporting infrastructure financing, including infrastructure bonds, real estate investment trusts, green bonds, state bonds and crowdfunding for small and medium-sized businesses. “What is needed is the pipeline of bankable, well-structured deals, and that’s where AIHN members come in,” Babaduko said.
SEC Director-General Emomotimi Agama said the success of the capital market should be measured by how effectively it enables Nigerians to participate in wealth creation and provides enterprises with access to capital. Small and medium businesses, which are important to the economy, need patient capital, crowdfunding channels and listing pathways suited to their size.
The human stakes are about retirement security and economic growth. A pension contributor in Lagos or Kano expects their savings to grow and to be available when they retire. If those savings sit in low-yield government securities because there are no alternative products, the contributor loses. If the savings are channelled into infrastructure that delivers power, roads and housing, the contributor gains and the economy grows.
Winners and Losers
Winners: Issuing houses, which gain a mandate to create new products and earn fees. Pension fund administrators, which gain investment options beyond government securities. Infrastructure projects, which gain access to long-term domestic capital.
Losers: Pension contributors, who face lower returns if the capital remains trapped in low-yield assets. The Federal Government, which loses a captive market for its debt if pension funds diversify. Small businesses, which remain starved of patient capital if the product pipeline does not expand.
Bottom Line: ₦32 trillion is not the problem. Finding somewhere productive to put it is. The pension industry has the capital. The capital market must build the products. Until it does, Nigeria’s savings will continue to underwrite government borrowing rather than economic transformation.